IN Brief:
- Beyond Oil reported third-quarter revenue of US$1.422m, up 22%, and a net loss of US$1.951m.
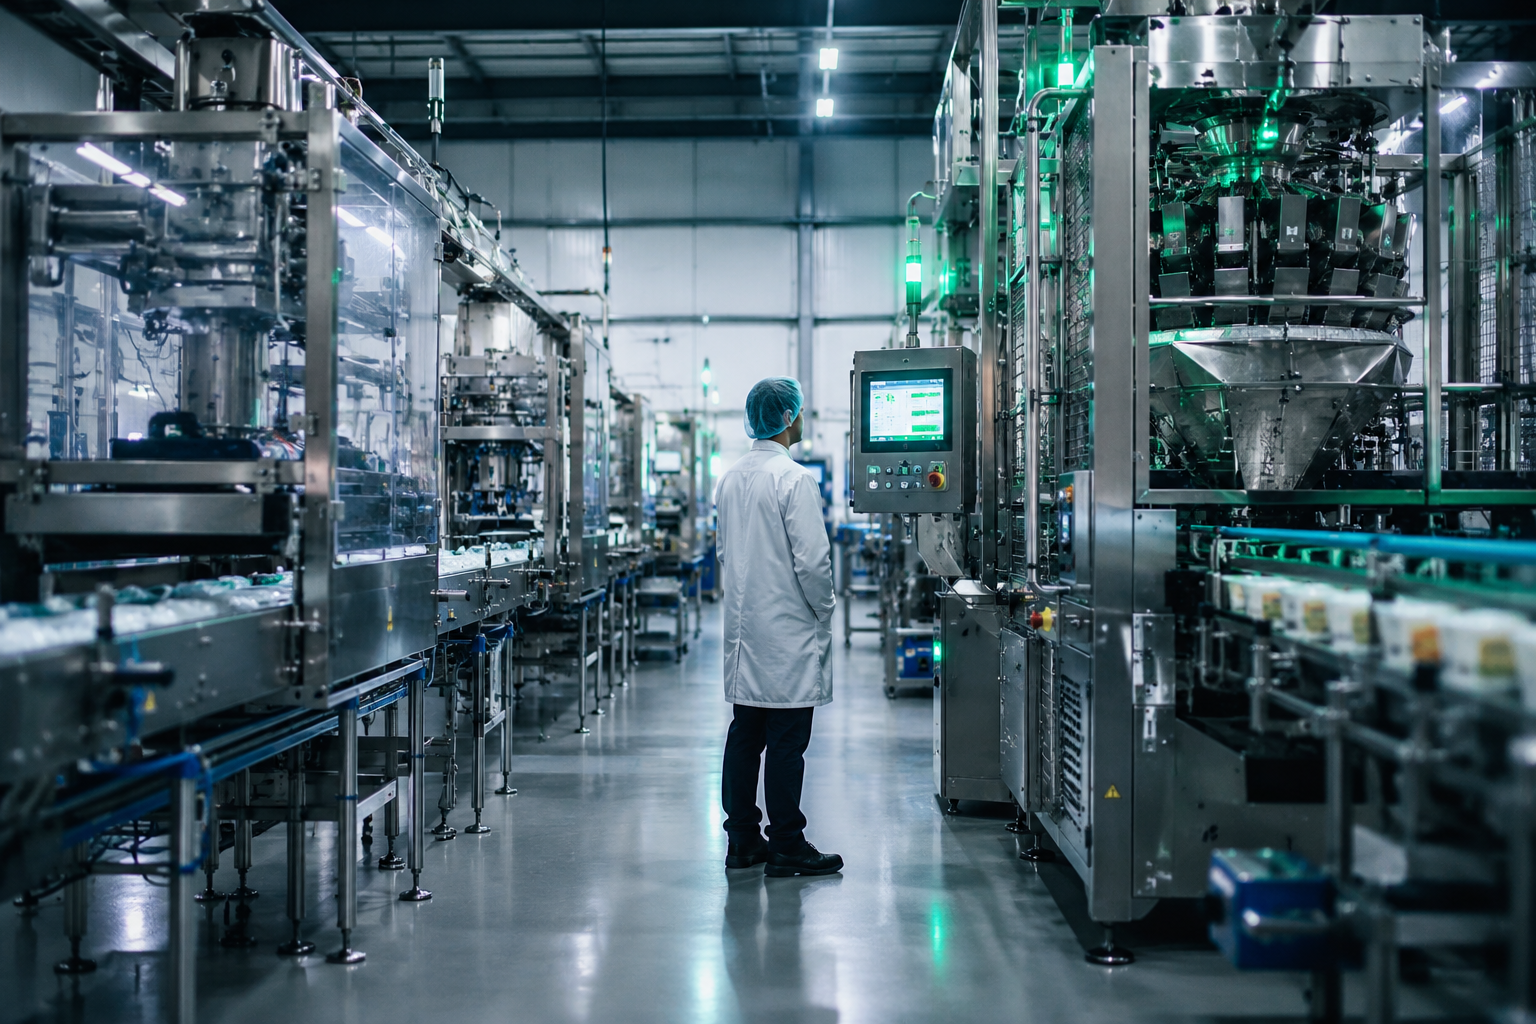
- Its first industrial customer adopted its filter-powder technology in October after an August pilot at a food manufacturing facility.
- The latest results report a 40.3% gross margin and discuss additional industrial opportunities without confirming a second factory customer.
Beyond Oil increased third-quarter revenue by 22% to US$1.422m, while gross margin declined and its net loss widened, according to results issued on 16 November. The frying oil treatment supplier is expanding its commercial channels and pursuing industrial food manufacturing opportunities, but its first factory adoption was announced in October rather than in the latest reporting period.
Revenue for the three months ended 30 September rose from US$1.168m a year earlier. Gross profit was US$573,000, compared with US$550,000 in the comparable quarter, and gross margin fell from 47.1% to 40.3%. The net loss widened to US$1.951m from US$1.545m. Revenue growth therefore occurred alongside pressure on profitability rather than an improvement across all financial measures.
For the first nine months of 2026, revenue totalled US$4.073m, up 24% from US$3.273m in the previous year. Quarterly operating expenses were US$2.693m, an 11% reduction from the second quarter but above the US$2.290m recorded a year earlier. Distribution partners continued to generate most revenue, although the company is developing direct relationships with large customers in the United States and elsewhere.
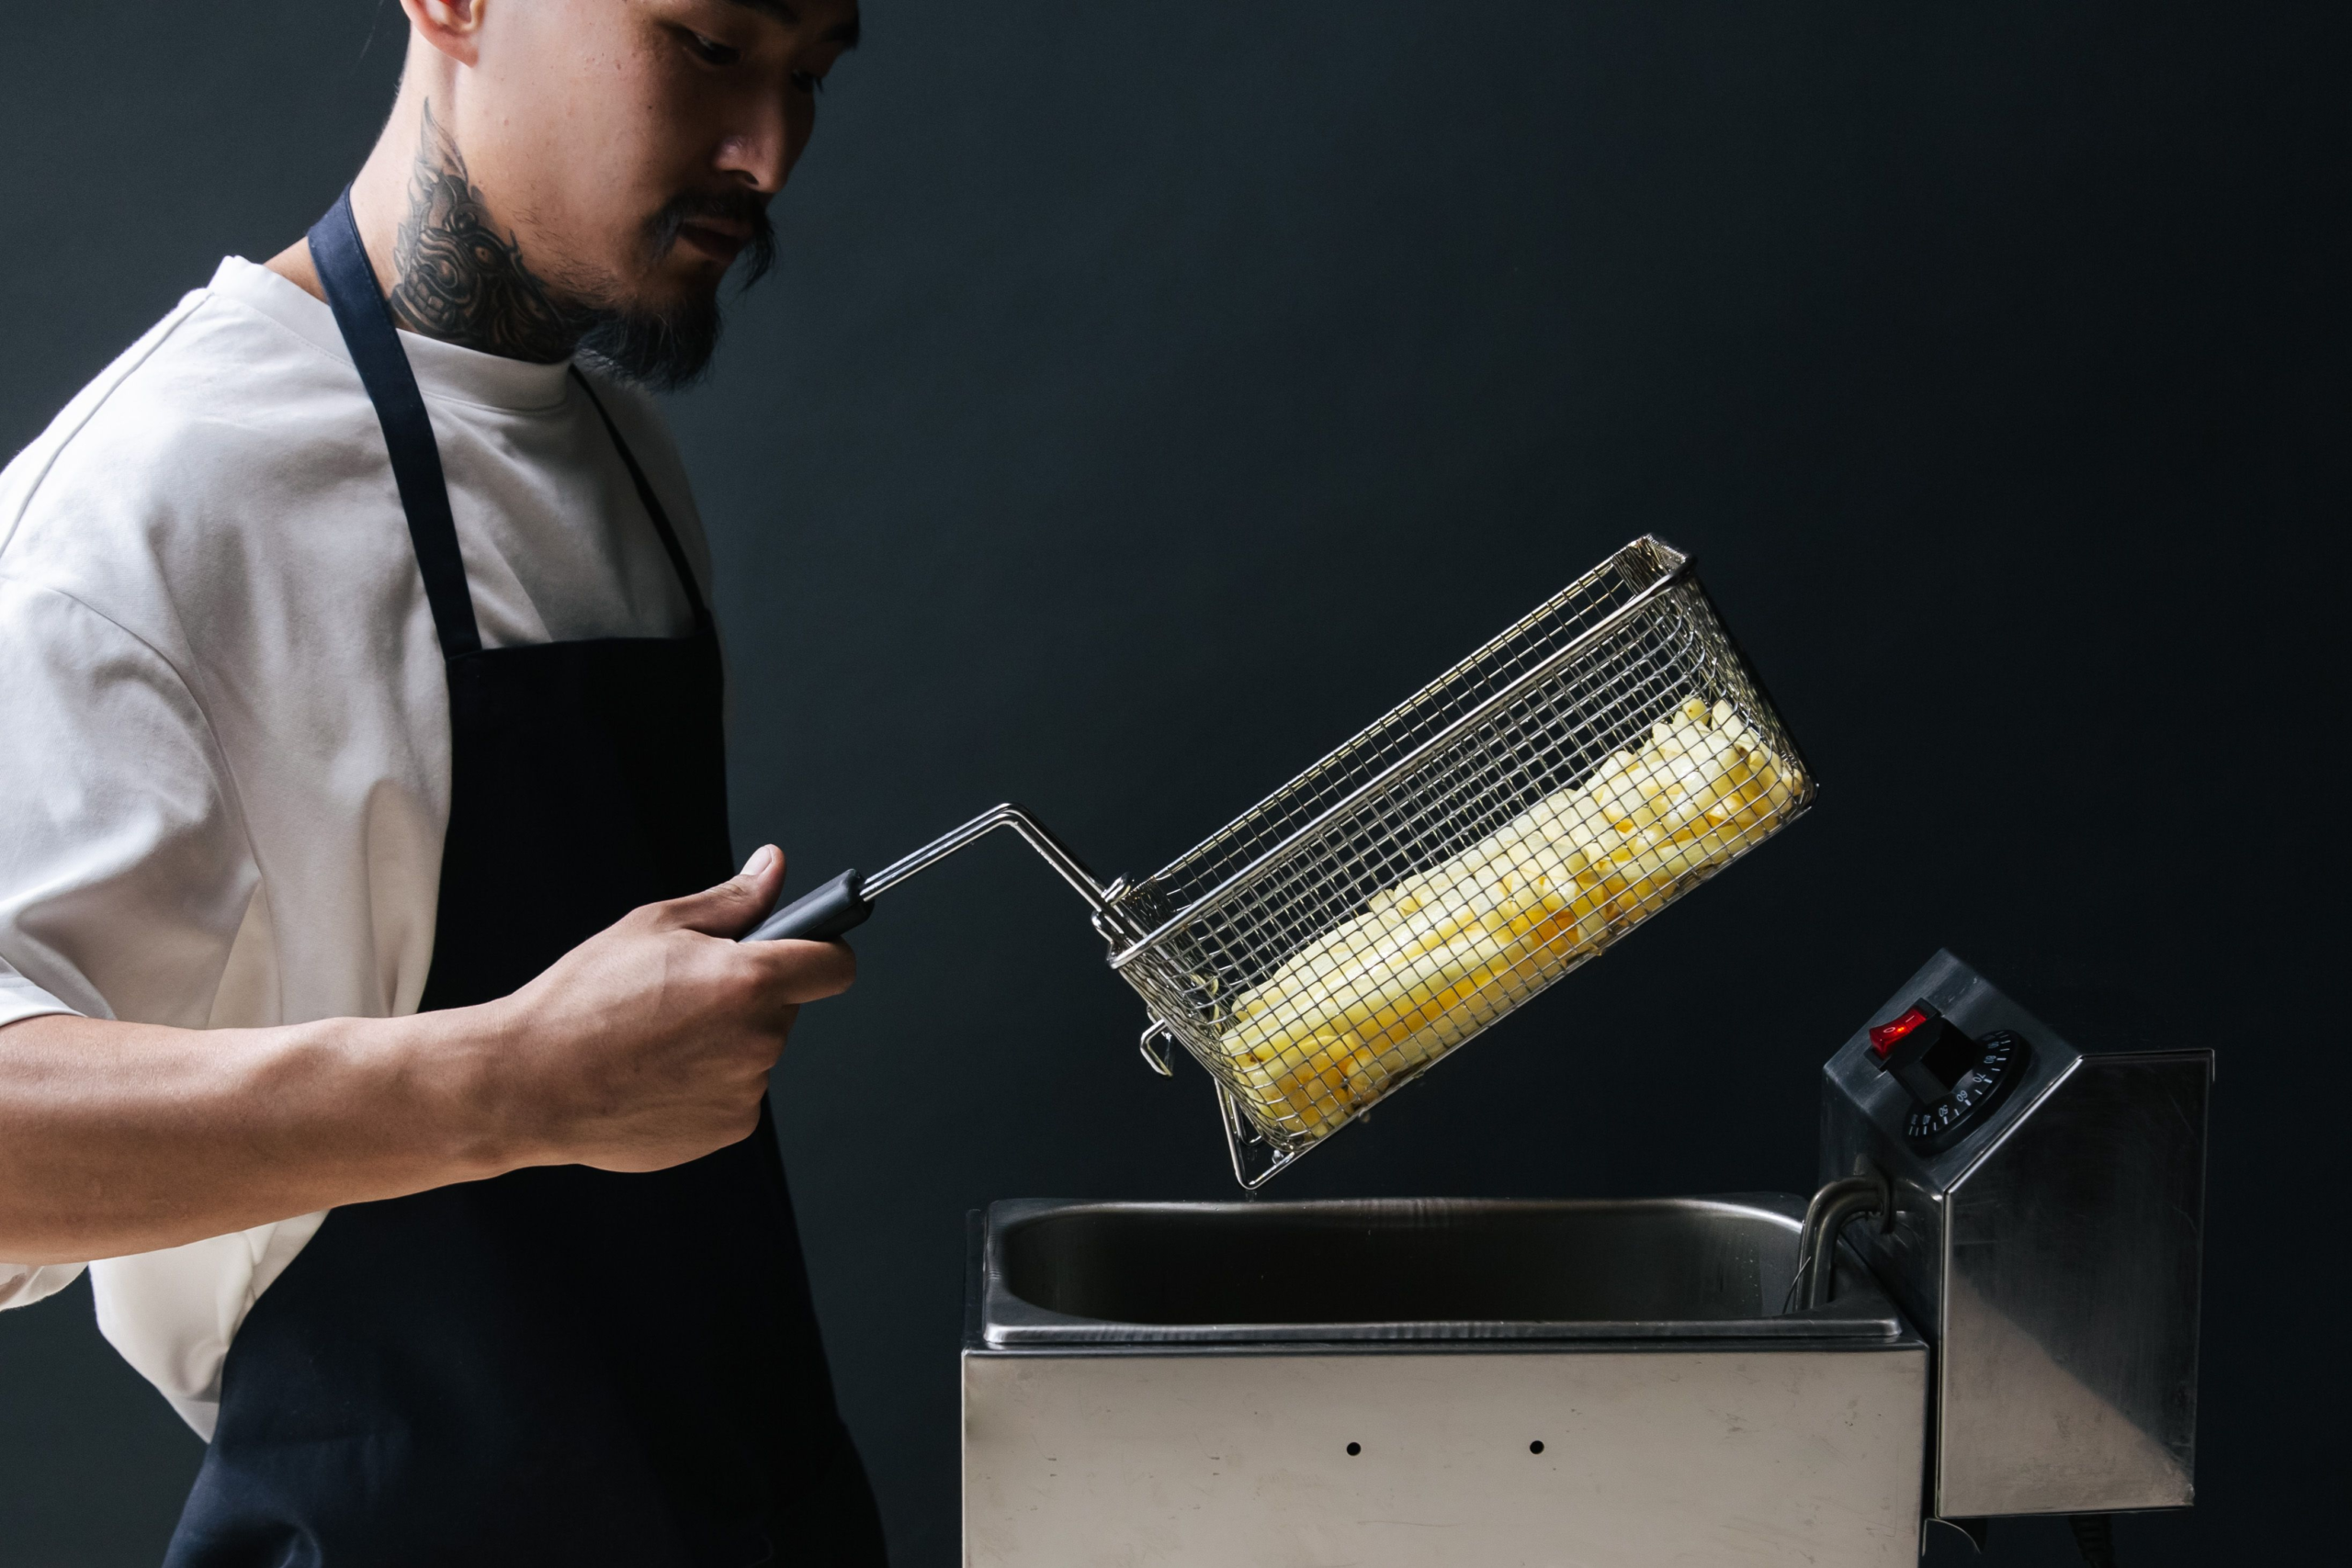
Beyond Oil supplies a filter-powder treatment intended to work within a fryer operator’s existing oil filtration process. Repeated heating and contact with food cause changes in frying oil composition, which can be assessed through measures such as free fatty acids and total polar compounds. The company is seeking to reduce degradation during use, but process conditions, the oil selected and the products being fried influence the outcome of any installation.
The company’s entry into industrial food production began with a pilot at an unnamed manufacturing facility. In August, Beyond Oil reported that oil treated with its technology had approximately 93% lower free fatty acid levels and 52% lower total polar compounds than an untreated control over the trial’s production cycle. Those percentages are comparisons within one trial, not measured cost savings or reductions that can be assumed across other frying plants.
Free fatty acids indicate aspects of hydrolytic oil breakdown, while total polar compounds reflect a wider group of degradation products formed during repeated frying. Both can inform an oil management programme, alongside operating temperature, filtration routines and product quality checks. The reported trial results do not specify a verified extension of oil life across a broader population of factories or quantify savings from lower oil disposal.
On 26 October, Beyond Oil announced that the host facility had completed implementation and integrated the treatment into its standard frying operations. That is the company’s first disclosed industrial customer; no second factory win was announced with the 16 November results. The operator’s name, production volume, contract value and any repeat order schedule have not been disclosed.
Use within standard production requires the treatment to fit the facility’s filtration and cleaning routines, with appropriate checks on oil condition and the finished food. Beyond Oil says its technology was integrated into the existing filtration workflow during the pilot. It has not published detailed installation parameters, a factory throughput figure or independent operating data covering an extended commercial period.
Industrial frying systems can circulate oil continuously and process substantial food volumes over long production runs. Filtration frequency, oil residence time, moisture introduced by the food and temperature control can all alter degradation rates. Data from a single industrial pilot therefore establish performance under the tested conditions without proving the same result for other equipment or product categories.
Most of the company’s November commercial updates relate to restaurants and food retail rather than factory production. These include approvals to supply larger restaurant systems and agreements for some franchise locations to begin using its product. An approval provides a route to future sales, but it does not establish that every restaurant in an approved network has placed an order or started installation.
Management expects direct sales and lower product production costs to support gross margin over time, although the latest quarter shows a decline. Distribution arrangements, product mix and initial market-entry pricing continue to affect realised margins. Industrial factory adoption remains a separate opportunity whose contribution to group revenue cannot yet be isolated from the published accounts.
At 30 September, Beyond Oil reported working capital of US$7.535m and cash plus short-term deposits of US$2.999m. It announced a proposed private placement of up to C$20m on 9 November, subject to the required exchange approval. The proposed financing is not money already received, and the company has not committed a disclosed portion specifically to industrial factory installations.
The company says additional industrial frying opportunities could lead to commercial activity during 2027. Its latest results do not identify a second factory, disclose recurring revenue from the first, or quantify production waste reductions achieved in normal operation. The August trial and October adoption remain the evidence for its industrial use; the 16 November report adds current financial results and management’s plans.
Further industrial deployment would be evidenced by additional named manufacturing customers, repeat orders and comparable process results under commercial operating conditions. The next accounts will also show whether the current shift in sales channels and product costs begins to reverse the decline in gross margin.