IN Brief:
- SIG will report through Aseptic Carton and Bag-in-Box & Spouted Pouch segments from its 2026 annual results.
- The company targets an 8–10% adjusted EBIT margin for Bag-in-Box & Spouted Pouch through operational and commercial improvements.
- A forecast €250 million fourth-quarter impairment is a non-cash accounting charge, not expenditure on restructuring or factory investment.
SIG is reorganising its packaging operations around two business segments, with manufacturing productivity, procurement savings and changes to its production footprint forming part of a programme to improve profitability. The Swiss group will report Aseptic Carton separately from Bag-in-Box & Spouted Pouch, giving each operation a clearer financial and management structure.
The changes were set out at SIG’s Capital Markets Day alongside medium-term financial targets and a turnaround plan for its flexible packaging activities. The new segment structure will be reflected in the company’s 2026 annual reporting. It also leads to an expected non-cash impairment of approximately €250 million in the fourth quarter, associated with the Bag-in-Box & Spouted Pouch and Chilled Carton businesses.
The impairment is an accounting adjustment to the value attributed to relevant assets, not a €250 million investment in factories or an equivalent cash payment to implement the restructure. SIG has not published a comprehensive breakdown of separate restructuring expenditure or identified every production site that may be affected by the planned footprint changes.
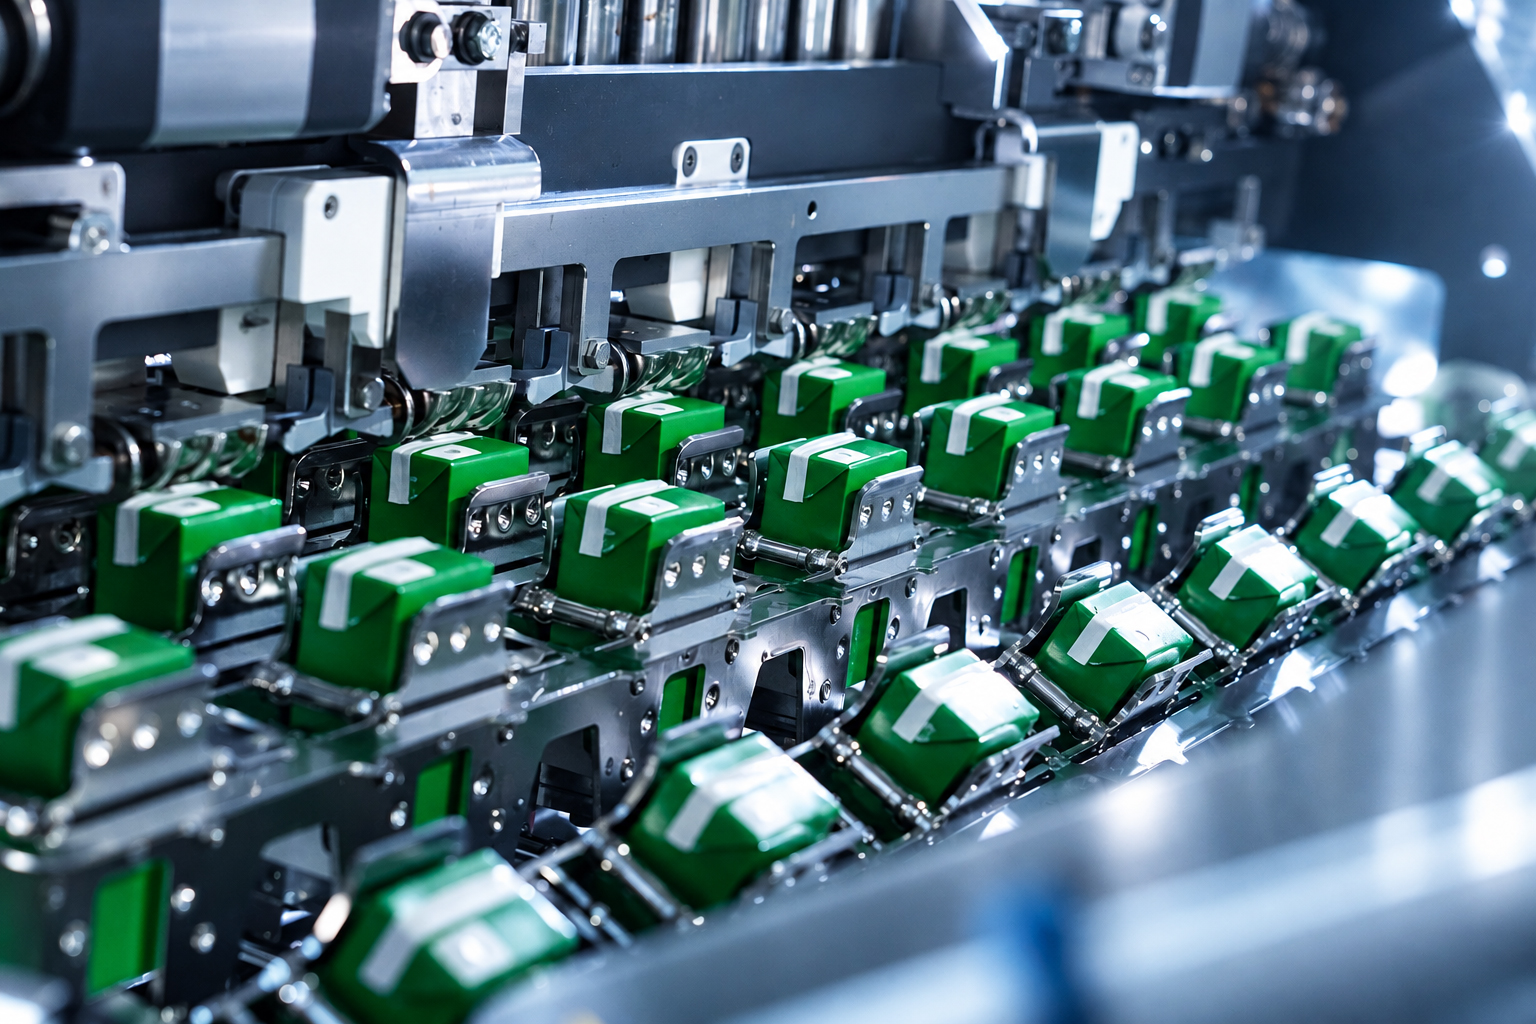
Within Aseptic Carton, the company is concentrating on systems used to package products including dairy drinks, juices and liquid foods. An aseptic packaging installation combines compatible packaging material, filling equipment and process controls that protect the product against contamination. Performance depends on maintaining the required conditions through packaging preparation, filling and sealing, as well as achieving the specified production rate.
SIG identifies its Neo filling platform and Terra packaging materials among the technologies intended to support this business. Neo focuses on filling performance and operational flexibility, while Terra includes carton structures designed to meet changing material specifications, including aluminium-foil-free full-barrier options. Those developments concern different elements of the packaging system and must be qualified together where a manufacturer changes its package or filling arrangement.
The company expects its underlying aseptic carton market to grow by approximately 2–3% over the medium term and aims to achieve an adjusted EBIT margin above 20% in the segment. These are management expectations, not production or profitability results already achieved. SIG has not assigned a specific additional filling capacity figure to the new organisational structure.
The more substantial recovery programme concerns Bag-in-Box & Spouted Pouch. SIG is establishing dedicated management for the business and intends to concentrate on differentiated applications, notably foodservice bag-in-box and aseptic spouted pouches. Its target is an adjusted EBIT margin of 8–10%, or 10–12% on a pro-forma basis before corporate allocations.
Bag-in-box packaging generally places a flexible container inside a supporting outer pack and is used for products including beverage concentrates and foodservice liquids. Spouted pouches combine a flexible structure with a dispensing fitment. Although both employ flexible materials, their manufacturing processes, filling interfaces and commercial applications differ, requiring separate assessment of equipment, packaging integrity and material performance.
In aseptic spouted-pouch operations, the package and filling process must meet requirements associated with product safety and the chosen preservation method. Reducing production costs cannot compromise sealing performance or the validated controls applied during filling. Changes in materials, equipment settings or suppliers therefore require qualification before they can be adopted across an established customer’s operation.
SIG’s turnaround measures include portfolio optimisation, organisational simplification, more efficient procurement and improvements to manufacturing and supply chain operations. The group also intends to optimise its production footprint, but has not disclosed a completed list of plant closures, transfers or capacity reductions. The stated measures describe a programme under development rather than a set of factory changes already delivered.
Production-footprint decisions can alter how components move between manufacturing sites and customers. Concentrating production may improve the utilisation of machinery, while increasing transport distances or reducing local flexibility. The result depends on actual order volumes, product specifications and the location of filling operations. SIG has not quantified an expected reduction in unit manufacturing cost from its proposed network changes.
Procurement measures are another part of the programme. Carton and flexible packaging systems rely on materials including polymers and paperboard, with supply arrangements affecting both cost and manufacturing continuity. Purchasing changes must account for material specifications, quality consistency and the need to qualify alternatives before they enter food packaging production.
The group is also seeking improvements in manufacturing performance and operating leverage. Higher utilisation can spread fixed costs across more saleable output, provided demand and material availability support the additional production. Equipment speed alone is not sufficient: downtime, waste, product changeovers and the proportion of material meeting specification also affect the cost of packaging produced.
SIG’s updated medium-term objectives include organic revenue growth of 3–5% at constant currencies and a group adjusted EBIT margin above 18%. These targets assume progress across both divisions, including the recovery of Bag-in-Box & Spouted Pouch and continued growth in Aseptic Carton. They should not be confused with the company’s separate guidance for its current financial year.
The company intends to reinstate dividends in 2027 in respect of the 2026 financial year, with a targeted payout ratio of 30–50% of adjusted net income. That proposal is a capital allocation objective, distinct from the operational savings and manufacturing changes under consideration.
The segment restructure will allow the performance of the two principal packaging businesses to be reported separately. Subsequent financial disclosures and factory-level implementation will determine whether the planned productivity improvements translate into higher margins, and which manufacturing locations, product lines or customers are affected by the operational changes.